Plan Design Consulting >
- 401k Plan design – The most important success measure of any retirement benefit plan is how successfully and efficiently it drives benefits to its participants. What are the most critical 401k plan design elements? What is the best way to structure 401k plan? How can you increase participant enrollment and thus maximize participant outcomes for retirement readiness? Whether the challenge is employee participation or higher contributions for executives, we can help make sure the plan is designed for maximum efficiency and effectiveness.
In our work with clients we have found that it is the design of the retirement plan that is one of the primary determinant of a plan’s effectiveness. Unfortunately, many employers focus nearly exclusively on the rate and methodology of the employer contribution while neglecting other factors that have an equivalent impact. Features such as automatic enrollment, automatic escalation, and plan leakage affect participant success as much contribution rate and methodology. Plan sponsors should evaluate the design of their plan with a lens focused on all the aspects of design that impact their employee retirement readiness.
At Kaizen Retirement Plan Advisors, we have extensive experience in the many different ways that a retirement plan can be designed. Whether the challenge is low deferral rates, lack of employee participation or lack of higher contributions for executives, we can help make sure the plan is designed for maximum efficiency and effectiveness, reduce leakage and most importantly drive successful participant outcomes!
- Defined Benefit and Cash Balance Plan design – a great benefit for employees and it’s certainly a differentiator in today’s 401k focused marketplace, but unfortunately it’s more complicated and technical than a 401k plan. Unlike the popular 401k plan, it requires the professional services of an enrolled actuary. Traditional defined benefit plan costs have soared over the past decade driven predominately by record low interest rates. None the less, there are many tactical strategies available to reduce cost of this benefit. From changes to the investment allocations, actuarial assumptions, funding, plan design and cash balance options, there are several methods to reduce pension expense.
- Money Purchase Plans, Target Benefit, Profit Sharing
Vendor Benchmarking, Search and Selection >
Selecting service providers is a serious fiduciary obligation and we see many plans that have been with the same provider for years and years and have never conducted a vendor due diligence review, despite the fact that the plan participants and assets may have grown substantially over the years. We will provide vendor analysis and comparison when needed, but no less seldom than once every three to five years. Often times, your existing provider will reduce fees for you because you put your plan thru the RFP process as they don’t want to lose your business. Because we are a plan level fiduciary with you and are always working in your best interest, we can be your advocate in interactions with vendors.
Some 401k recordkeepers have special niches that they provide to separate themselves from the hundreds of providers that are out there. For example, outsourcing administrative functions (known as 3(16) services) such as eligibility, entry dates, loans, participant fee disclosure and other required notices are gaining in popularity. If a new provider is desired, we help clients develop selection criteria that maps to their organizational goals and needs, guide them through the vendor evaluation process, provide recommendations, and help them manage the conversion process once they’ve made their decision.
Our value doesn’t end there. We will help you evaluate your service providers on an ongoing basis to ensure they are charging a reasonable fee, benchmarked to industry standards. We will also monitor service quality, so you can use your valuable time managing your business.
PARTICIPANT EDUCATION
At Kaizen, we understand that education to your employees is where the rubber meets the road. The best 401k plan in the world is lousy if participation is low. A plan will only be considered a great plan if your employees think it is great and thus participate at a meaningful level.
Many vendors in the retirement market space limit their employee education to their website with a standard retirement calculator and risk based questionnaire and access to the fund fact sheets and prospectuses. Others will provide participant education virtually in order to reduce their costs and improve their profit margins. That’s all fine and good. But ask yourself, have these methods of education inspired your employees to take their retirement savings to the next level? Probably not.
At Kaizen, we will execute a participant engagement strategy that delivers better results than generic education. With an engaging presentation with easy to understand language, we can take your participation rate and deferral rates to the next level. Our clients average 95% participation and more than 7% average deferral rates. We will meet with your employees one on one for the personal attention they may need. For so many Americans, the 401k is often their biggest personal asset. Should they be directed to a website or logon to a WebEx or virtual meeting to discuss their biggest asset? We don’t think so.
Additionally, there is a domino effect with employee participation rates and deferral rates that perhaps you might want to consider. Higher participation rates produce higher average deferral rates. Higher average deferral rates translate to highly paid employees (defined as 120k in total compensation) saving more as well due to non-discrimination testing limits. In addition, this has an impact on vendor pricing as many vendors price a plan based on average participant balances and annual cash flow from employee and employer contributions. Plans with higher average participant balances and higher annual cash flows get better pricing.
Fee disclosure
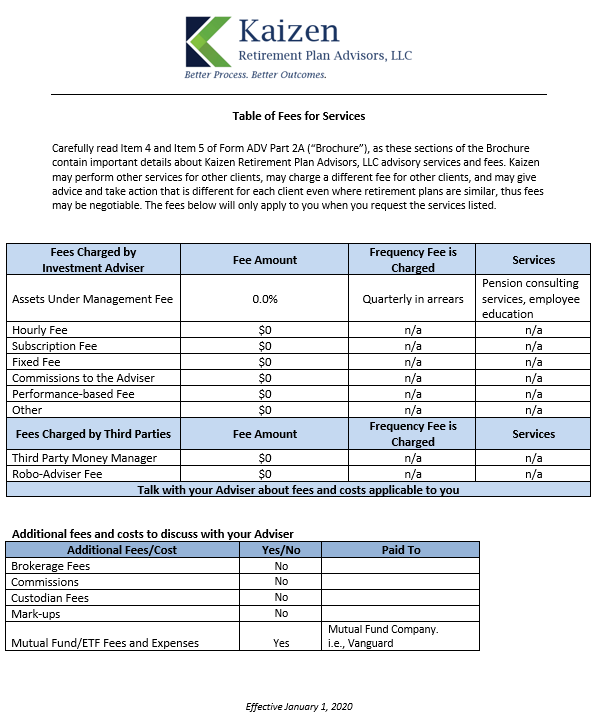
Kaizen takes pride in it’s role to provide clear, customized and relevant advice with a detailed fee disclosure. We will provide you a simple one page fee disclosure as seen below. This is in addition to providing you our ADV and firm brochure.